
India’s primary market has delivered one of the clearest contradictions in the country’s financial markets this year.
While the secondary market has struggled with foreign investor outflows, elevated oil prices and global interest-rate uncertainty, companies have continued to raise extraordinary amounts of money.
Indian firms raised a record ₹2.43 lakh crore through public equity markets between April and September 2026, the first half of FY27, according to data from PRIME Database Group. The total was roughly 75% higher than the corresponding period a year earlier.
The scale of the fundraising matters because it came during a period when investor sentiment in listed equities was far from uniformly strong.
The Nifty 50 gained only about 1.3% during the six-month period, yet demand for new issues remained strong enough to absorb some of the largest Indian IPOs in recent years.
That suggests India’s IPO market is increasingly developing a momentum of its own.
Mainboard IPO Fundraising Hits a Record
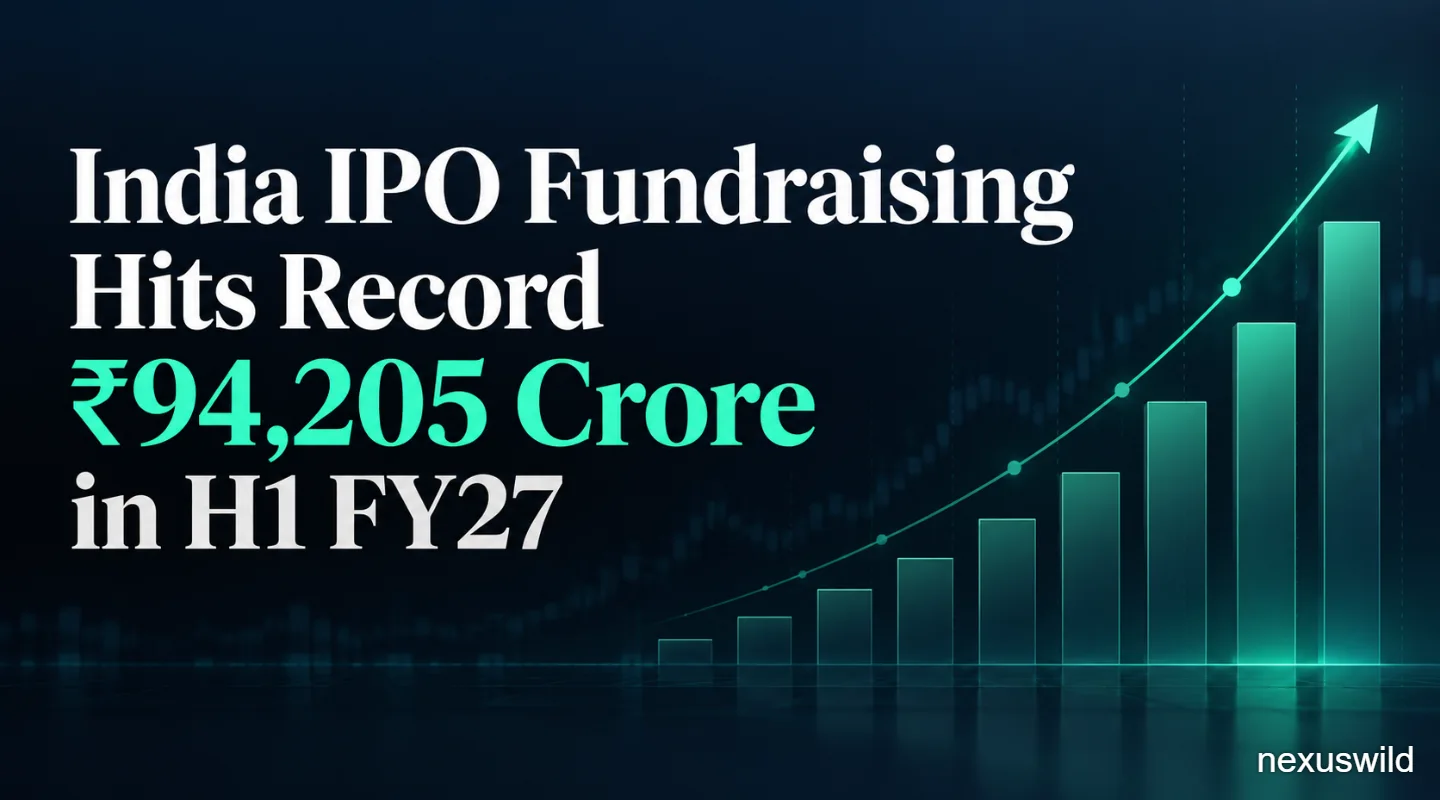
Mainboard companies raised ₹94,205 crore through 78 IPOs during April-September 2026.
That was around 35% higher than the previous first-half record of ₹69,533 crore raised through 65 IPOs in the same period of FY26.
The number is particularly striking because the financial year began slowly.
Only about ₹3,794 crore was raised through mainboard IPOs during the first three months of FY27, according to PRIME Database Managing Director Pranav Haldea.
Activity accelerated sharply thereafter as several long-awaited companies entered the market.
Among the biggest was the National Stock Exchange of India, whose ₹22,563 crore offering became one of the largest IPOs in Indian market history.
SBI Funds Management followed with an issue worth about ₹9,795 crore, while Manipal Health Enterprises raised roughly ₹9,275 crore.
Those three deals alone accounted for a substantial portion of the half-year fundraising.
Why IPO Demand Stayed Strong
The obvious question is why companies have found so much demand when the broader market has remained volatile.
One explanation is domestic liquidity.
Indian mutual funds, institutional investors and individual investors have become an increasingly important source of capital in the equity market.
Regular inflows through systematic investment plans have helped domestic institutions deploy money even when foreign investors have been more cautious.
Market participants cited by Reuters and Mint said this pool of domestic capital has helped companies launch large public offerings without depending as heavily on overseas investors.
There has also been a backlog of companies waiting to list.
Several businesses had prepared IPO plans over the previous two to three years but postponed them because of valuation concerns, geopolitical uncertainty or weak market conditions.
As that pipeline finally began moving, multiple large transactions reached investors within a relatively short period.
India’s securities regulator also granted a one-time extension earlier in 2026 for certain IPO approvals that were approaching expiry after companies delayed their offerings amid geopolitical turbulence.
Investors Are Still Chasing New Listings
Demand has not merely been sufficient to complete deals.
In many cases, it has been intense.
Among 64 IPOs for which subscription data was available, 42 were subscribed more than 10 times, according to PRIME Database.
Twenty-five of those offerings received bids exceeding 50 times the number of shares available.
Average listing gains also increased sharply.
Shares in the group of IPOs for which data was available delivered an average first-day gain of about 19%, compared with roughly 7% during the corresponding period a year earlier.
That performance has helped keep investor interest alive.
But listing gains should not be confused with guaranteed long-term returns. IPO shares can become volatile after listing, particularly when valuations are aggressive or broader markets weaken.
The Record Is Bigger Than IPOs Alone
The ₹2.43 lakh crore headline number includes more than traditional IPOs.
Companies also raised money through qualified institutional placements, secondary share sales, SME IPOs and listed investment vehicles.
Qualified institutional placements, or QIPs, rose around 36% to ₹61,553 crore during the first half, with Adani Enterprises among the major fundraisers.
Secondary share offerings were even more significant.
They increased roughly fivefold to ₹55,337 crore, helped by government stake sales in companies including Life Insurance Corporation of India and Coal India.
The government's 6.5% stake sale in LIC alone raised approximately ₹31,400 crore.
This matters because the fundraising boom is serving several different purposes.
Some companies are raising fresh capital to expand operations, reduce debt or finance acquisitions.
Others involve existing shareholders selling stakes.
Government divestments represent another category altogether.
Investors therefore need to distinguish between money entering a company and proceeds going to existing shareholders.
New Sectors Are Reaching Public Markets
Another reason the IPO pipeline has attracted attention is the range of businesses entering the listed market.
Traditionally, major Indian indices have been dominated by financial services, energy, industrial companies, IT services and consumer businesses.
Recent IPOs have offered exposure to businesses that were previously difficult for public-market investors to access.
Reuters highlighted companies including furniture-rental platform Rentomojo, supply-chain asset pooling company LEAP India and Asset Reconstruction Company (India) as examples of relatively specialised businesses entering public markets.
That creates an additional attraction for investors.
An IPO is not just another stock when it provides exposure to an industry or business model that has little representation among existing listed companies.
India’s IPO Pipeline Remains Enormous
The second half of FY27 could remain active.
Nearly 250 companies are preparing IPOs that could collectively raise about ₹4.65 lakh crore, according to PRIME Database data cited by Reuters.
Business Standard separately reported that 145 companies with plans to raise about ₹2.78 lakh crore had already received regulatory approval, while another 102 companies seeking approximately ₹1.87 lakh crore were awaiting clearance.
Several potentially significant names are part of the broader pipeline.
These include Jio Platforms, Carlsberg’s India business and Oyo parent Prism, according to Reuters.
Jio Platforms alone has been associated with a potential offering of roughly $3.8 billion.
If even part of this pipeline reaches the market, 2026 could reinforce India's position as one of the world's most active equity-fundraising destinations.
What Could Slow the IPO Boom?
The current momentum is substantial, but it is not risk-free.
A sharp deterioration in the secondary market could make investors more reluctant to pay premium valuations for newly listed companies.
Oil prices remain an important concern for India because the country imports much of its crude.
Higher energy prices can pressure inflation, weaken the rupee and affect corporate margins.
Global interest rates are another risk.
Higher bond yields can reduce the relative attractiveness of equities and raise financing costs across the economy.
Geopolitical developments could also quickly change risk appetite.
Companies planning IPOs therefore still have to balance the desire to raise capital with the possibility that market conditions could change before their issue opens.
A Deeper Shift in India’s Capital Markets
The more important story behind the record numbers may be structural.
India is gradually developing a deeper domestic capital pool capable of financing businesses at a scale that previously depended more heavily on foreign institutional investors.
That does not mean foreign capital has become unimportant.
But domestic mutual funds, pension-linked savings, insurance capital and individual investors now play a larger role in absorbing new share supply.
This is allowing companies to access public capital even during periods when the benchmark indices are struggling.
It also creates a different relationship between the primary and secondary markets.
Historically, a weak stock market often meant companies postponed IPOs almost automatically.
The first half of FY27 has shown that the relationship is no longer quite so straightforward.
Conclusion
India’s record ₹2.43 lakh crore equity fundraising in H1 FY27 is more than an IPO statistic.
It reflects a growing domestic investor base, a long backlog of companies seeking public capital and a market that is becoming large enough to absorb billion-dollar offerings even during periods of volatility.
The ₹94,205 crore raised through mainboard IPOs is already a first-half record, while the pipeline suggests more large listings could follow.
The next test will be whether demand remains equally strong if global financial conditions become more difficult.
For now, however, India’s primary market is sending a clear signal: companies are finding plenty of capital even when the broader stock market is giving investors reasons to be cautious.
Nexuswild welcomes factual corrections. Email contact@nexuswild.com with evidence and the article URL.