
Artificial intelligence competition is changing the cloud computing industry, pushing major technology companies to rethink how they sell computing power, distribute AI models and attract business customers. Cloud providers are no longer competing only on storage, servers and software services. They are increasingly competing to become the platforms where companies develop, deploy and manage AI applications.
The shift is creating an unusual business environment in which companies can compete in AI development while cooperating on infrastructure and distribution. OpenAI, for example, plans to make its advanced models available through Google Cloud, even as Google continues to develop its own competing AI systems. The move follows OpenAI's expansion of model distribution through Amazon Web Services after its exclusive distribution arrangement with Microsoft expired in April 2026. <Cite refs={["turn111924news20"]} />
This changing relationship reflects a broader industry trend: access to powerful AI models is becoming a key part of cloud services, while the cost of running those models is increasing the importance of computing infrastructure, pricing and enterprise relationships.
Cloud Providers Are Becoming AI Distribution Platforms
For years, major cloud companies built their businesses around providing computing resources, databases, storage and software tools over the internet. AI has added another layer to that model.
Businesses increasingly want to access AI models through services they already use, rather than build and maintain all the necessary infrastructure themselves. Cloud platforms can offer a single environment for model access, data management, security controls, billing and application development.
OpenAI's planned availability on Google Cloud illustrates this approach. Enterprise customers will be able to access models through Google's Model Garden and Cloud Marketplace, while eligible customers can use existing cloud spending commitments for purchases.
The arrangement also allows organisations in regulated industries to use cloud-based access controls and data-governance tools when developing AI applications.
For Google, offering models from an outside developer broadens its cloud portfolio. For OpenAI, the agreement creates another route to enterprise customers. Both companies can benefit from the relationship even as they compete in other parts of the AI market. <Cite refs={["turn111924news20"]} />
Amazon, Microsoft and Google Face a Changing Competitive Landscape
Amazon Web Services, Microsoft Azure and Google Cloud have become central players in the commercial AI market because they control large computing infrastructures and already serve businesses across industries.
Each provider has invested in AI infrastructure, model development or partnerships that help customers build and run AI-powered applications.
Microsoft has maintained a close relationship with OpenAI and integrates AI capabilities into its cloud and enterprise software offerings. Amazon has invested in Anthropic and offers AI models and development tools through AWS. Google combines its own AI models with a cloud platform that also supports third-party models.
These strategies reflect different approaches to the same opportunity. Providers can compete by developing proprietary models, offering access to outside developers' models, supplying specialised computing hardware or integrating AI into existing enterprise services.
The result is a more complex market in which cloud companies may cooperate with businesses that are also their direct competitors. The companies that attract enterprise spending will depend not only on model performance but also on price, reliability, security and ease of integration.
AI Computing Costs Are Reshaping Cloud Economics
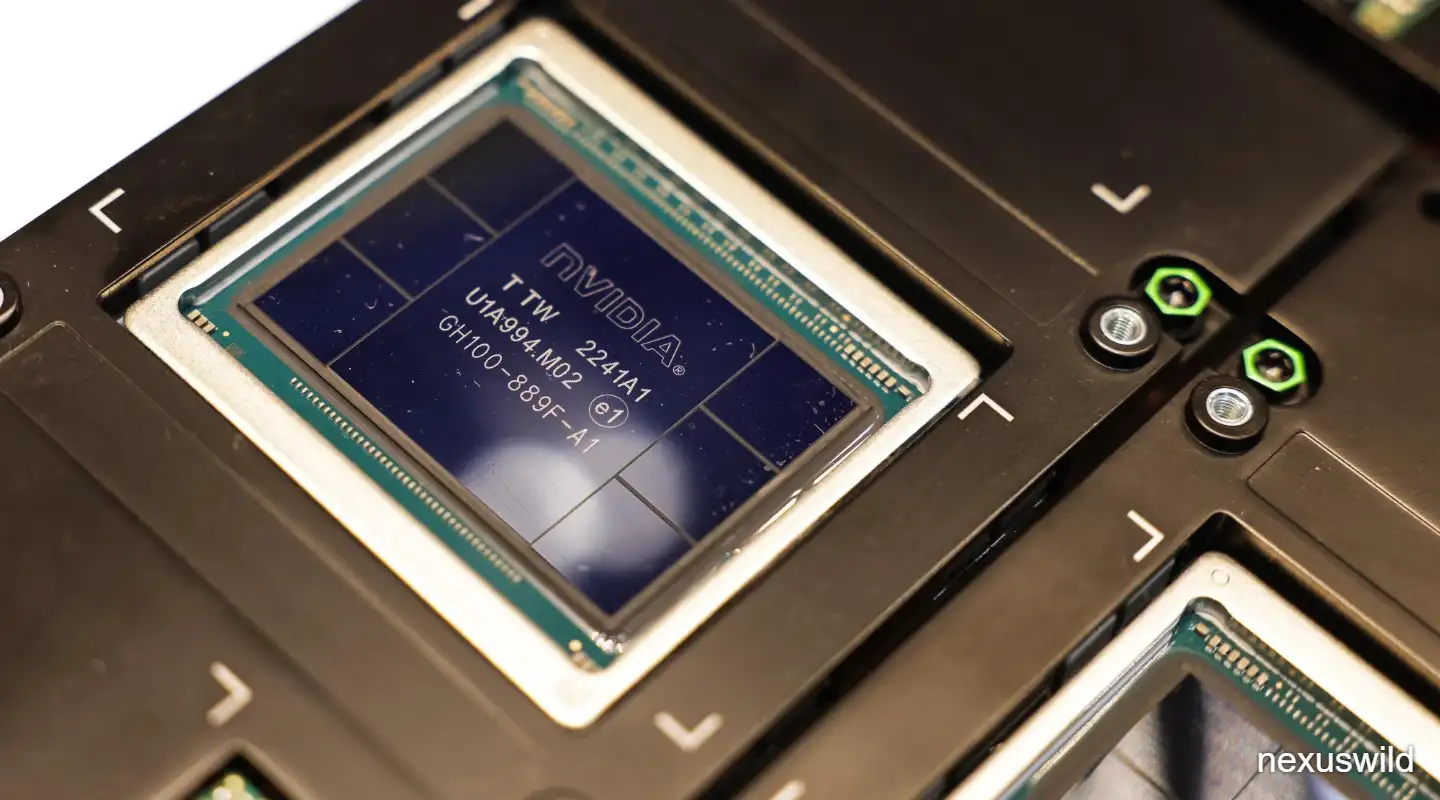
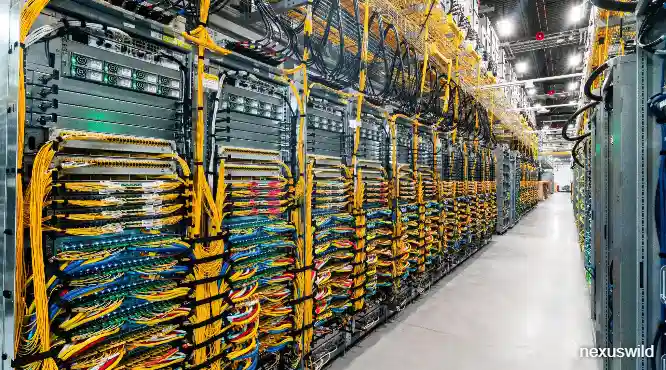
AI models require substantial computing resources, particularly during training and when serving large numbers of user requests. Cloud providers are investing in data centres, advanced chips, networking equipment and power infrastructure to support this demand.
However, the economics of AI are changing as businesses move from experimenting with models to deploying them in everyday operations.
Training involves using computing resources to develop or improve a model. Inference is the process of running a trained model to generate responses, analyse information or perform tasks. As AI applications reach more users, inference can become a major and recurring source of computing demand.
A McKinsey analysis published on October 5, 2026, projects that inference could account for around 60% of AI computing demand by 2030, compared with approximately 40% for training. The estimates highlight why cloud providers are paying increasing attention to the cost of delivering AI services at scale. <Cite refs={["turn111924search3"]} />
For customers, the relevant question is increasingly how much it costs to achieve a useful outcome, not simply how powerful a model appears in a benchmark. Providers that improve computing efficiency, reduce latency and match the right model to each task may be better positioned to serve different workloads.
Smaller AI Cloud Providers Are Entering the Market
The competition is not limited to the largest technology companies. Specialised cloud providers, often called neoclouds, focus on supplying computing infrastructure designed for AI and other demanding workloads.
These companies typically emphasise access to graphics processing units (GPUs), high-performance computing, flexible capacity and infrastructure tailored to AI applications.
Gartner forecast in June 2026 that neocloud providers could capture 20% of a projected $267 billion AI cloud market by 2030. This is a forecast rather than a confirmed outcome, but it illustrates the potential scale of competition from specialised providers. <Cite refs={["turn111924search2"]} />
Specialists may appeal to businesses that need particular types of AI computing capacity or want alternatives to the largest cloud platforms. However, they also face challenges involving capital requirements, hardware availability, reliability and the ability to compete with established providers' broad service portfolios.
For enterprise customers, the growth of these alternatives could create more choices, although switching costs and technical dependencies may still make it difficult to move workloads between providers.
Businesses Want More Choice, but Vendor Lock-In Remains a Risk
As more AI models become available through cloud platforms, businesses can compare different systems for tasks such as software development, customer support, document analysis and data processing.
A company might choose one model for coding, another for summarising documents and a third for a specialised industry application. This approach can help organisations balance cost, speed, accuracy and security requirements.
However, deploying AI across several platforms can introduce additional complexity. Different models may use different interfaces, data formats, pricing structures and security controls. Businesses must also consider where data is processed and whether their applications can be moved if a provider changes its prices or terms.
Vendor lock-in remains an important concern when applications depend heavily on a specific provider's tools or proprietary infrastructure. Using common interfaces, portable application designs and clear data-export procedures can reduce some of these risks, although they cannot eliminate every switching cost. <Cite refs={["turn111924news9"]} />
Cloud providers therefore have an incentive to offer a broad selection of models while also encouraging customers to build applications around their own platforms. For customers, the challenge is to benefit from choice without creating an overly complicated technology environment.
What the Shift Means for the Future of Cloud Computing
AI model competition is expanding the role of cloud computing from infrastructure rental to a broader service that combines models, computing power, data tools, security and application development.
This shift could create opportunities for established cloud providers, specialised infrastructure companies and AI developers. It may also increase pressure on providers to offer competitive prices, reliable services and simpler ways for customers to use different models.
The market's next phase will depend on whether enterprise demand grows quickly enough to justify the large investments required for AI infrastructure. Providers must also demonstrate that their services can deliver measurable business value rather than simply attract attention through model releases and computing capacity.
The emerging landscape is not one in which a single company necessarily controls every layer of AI. Instead, model developers, infrastructure providers and enterprise software companies are increasingly connected through partnerships and competition.
As AI adoption expands, the cloud computing business will increasingly be shaped by which platforms can deliver useful AI capabilities securely, efficiently and at a cost businesses are willing to pay.
Nexuswild welcomes factual corrections. Email contact@nexuswild.com with evidence and the article URL.