
Global Semiconductor Stocks Plunge 12.2% as AI Investment Concerns Trigger Market Selloff
semiconductor stocks fell sharply on November 5. Investors looked again at the future of intelligence infrastructure spending and also reacted to bad news from some parts of the chip industry.
The Philadelphia Semiconductor Index, known as SOX is a benchmark for big US semiconductor companies. It fell 12.2% that day. Reuters said this was the single‑day drop for the index since April 2025. The fall is a reversal for a sector that had grown because of strong demand for AI processors, memory and data‑centre hardware.
The larger US stock market also slipped. The Nasdaq Composite dropped 5.5%. The Nasdaq‑100 fell 6.4%. The S&P 500 fell 4.4%. The Dow Jones Industrial Average fell 3.4%. The Nasdaq Composite closed than 10% below its recent record high, which is the usual definition of a market correction.
Major Chipmakers Face Steep Share-Price Declines
The selloff hit companies along the semiconductor supply chain. That includes processor designers, memory manufacturers and suppliers of chip technology.
Advanced Micro Devices or AMD fell 17.3%. Micron Technology fell 17.5%. Arm Holdings lost 13.1%. Broadcom fell 10.4%. Nvidia fell 9.3%.
The size of these falls shows how fast investors were pulling back from companies tied to the AI infrastructure investment cycle. Semiconductor shares had grown because investors expected cloud providers and technology companies to keep spending on large‑scale AI computing.
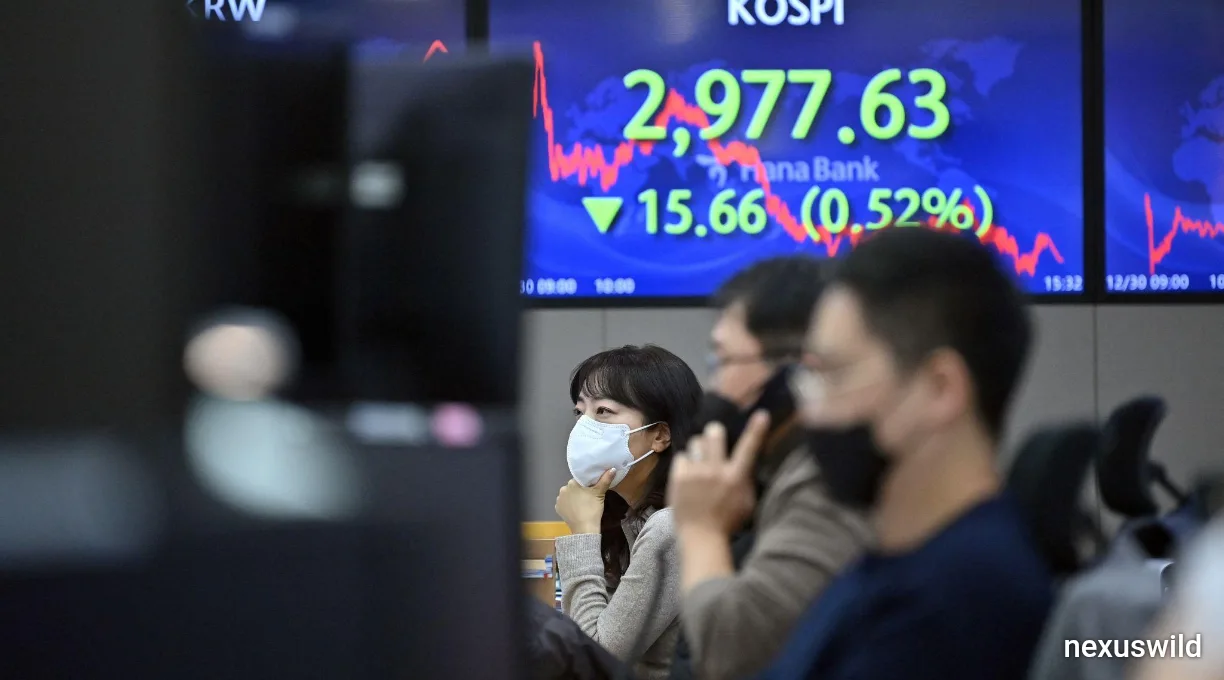
The losses were not in the United States. South Koreas KOSPI index fell 5.28%. SK Hynix also fell a lot. In Japan Advantest, a supplier of semiconductor testing equipment was one of the companies hit by the technology selloff.
These moves show how far the semiconductor supply chain reaches. Chip designers, memory manufacturers, equipment suppliers and data‑centre infrastructure companies are linked by investment decisions and demand expectations in major markets.
Qualcomm Results Add Pressure to the Sector
Qualcomms recent financial outlook added to the negative feeling in the market.
The company said that smartphone chip sales were below what Wall Street expected. This raised worries about demand and about component costs. Qualcomms shares fell 9.5% on November 5.
Arm Holdings also faced scrutiny from investors after its revenue guidance did not meet the high expectations of the market. Even though the company’s forecast was a bit above the consensus estimate investors had been hoping for an outlook because of optimism about AI demand.
These events put pressure on a sector that was already being re‑valued. In markets where share prices had risen a lot because of hopes for growth results that are technically better than analyst estimates can still cause selling if investors had already priced in even better outcomes.
AI Infrastructure Spending Becomes a Central Market Concern
Beyond the results of companies investors are asking whether the quick growth of AI infrastructure will bring in enough money to justify the large amount of investment.
Big cloud and technology companies have put a lot of money into data centres, advanced processors, networking equipment, power infrastructure and other supporting systems. These investments are meant to meet the growing demand for AI services and for more computing power.
Spending on infrastructure does not automatically bring in immediate revenue or profits. Investors are looking closely at how fast AI services can bring in regular income whether customers will pay enough to cover the computing costs and how long it will take for big infrastructure projects to give good returns.
Concerns about how much capital's needed are also growing. Building and running AI data centres costs a lot of money on electricity, cooling, land, networking and hardware. If revenue growth does not match these costs companies may feel pressure on cash flow. On returns from investment.
This does not mean that AI demand is getting weaker or that the current infrastructure investment will fail. Instead the market reaction shows that investors are paying attention to the financial assumptions behind future spending.
US Political Developments Add Uncertainty to Data‑Centre Expansion
The selloff on November 5 also showed that investors were worried about how US politics might affect AI infrastructure projects.
Democratic wins in the November 3 midterm elections raised questions about whether political opposition to some data‑centre projects could lead to local rules longer approval times or more conditions for new projects.
Some candidates campaigned on worries, about electricity demand, water use and the local impact of data‑centre projects. Market participants are looking at whether those positions could change construction plans in places where AI infrastructure investment's focused.
The difference between proposals and rules that are actually made into law is important. The outcome of elections does not automatically create rules for data centres across the whole country. Each project still has to go through planning, permitting and the electricity network rules.
However the chance of delays or higher costs for building can affect what investors expect from companies that supply chips, networking gear and other infrastructure parts.
What the Selloff Means for the Semiconductor Industry
The sharp fall shows how sensitive the value of semiconductor companies is to changes in what people expect.
Companies that make AI processors and memory items depend on demand forecasts that rely on the ongoing investment from a small group of big technology customers. If those customers spend delay projects or ask for better prices the impact can spread through the whole supply chain affecting chips and other components.
For semiconductor makers, equipment suppliers and investors in technology the main questions now are whether spending on AI infrastructure will stay strong how fast new computing capacity will bring in money and whether the industry can keep its profit margins on chips as competition and the need for capital grow.
The fall on November 5 alone does not prove that AI demand has collapsed or that semiconductor fundamentals are getting worse in the run. It does show that investors are rethinking how expected AI growth, company earnings and the huge capital commitments that back the sector are connected.
What to Watch Next
Investors will keep an eye on the earnings reports the capital spending plans of hyperscalers the growth of AI related revenue and any changes that affect data‑centre approvals in the United States especially for chips.
The next phase of the semiconductor market will rely on more than the demand, for advanced chips. It will also depend on whether investing in AI infrastructure can bring in commercial profits for chips.
Nexuswild welcomes factual corrections. Email contact@nexuswild.com with evidence and the article URL.