
For consumer brands, the easy phase of pricing is over. Raising list prices across the board worked while shoppers were still adjusting to inflation. With costs rising again and household budgets stretched, companies are leaning on subtler tools: pack sizes, product mix and targeted promotions. The picture varies sharply by category and region.
What inflation looks like now
US consumer prices rose 3.7 percent in the 12 months to September 2026, according to the Bureau of Labor Statistics. Energy was the driver, up 20.4 percent on the year and 5.2 percent in the month. Core prices, excluding food and energy, rose 2.6 percent, and food at home rose 1.8 percent.
That mix matters for brands. Grocery prices themselves are not climbing fast, but the costs of oil-linked inputs such as packaging, freight and manufacturing are. Brands face rising costs without a clear opening to pass them on.
Cost pressure is returning
First-quarter results from major consumer goods companies, summarised by Accuris, showed the squeeze. Colgate cut its gross margin guidance, citing a $300 million headwind. Reckitt modelled a £130 million to £150 million impact if oil stays at $110 a barrel. Coca-Cola HBC expected a low single-digit rise in cost per case.
Mondelēz showed the strain in chocolate, where cocoa costs remain elevated. Its adjusted operating income fell 19 percent at constant currency, and chocolate volume and mix fell 2.1 points, according to the same summary. Those figures are secondary and include calendar effects, such as Easter timing, that flatter some volume numbers.
From list prices to price-pack architecture
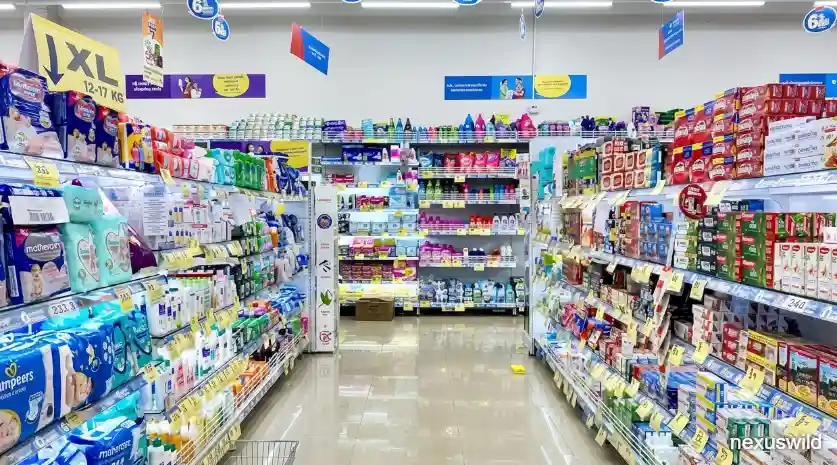
The most visible shift is in how brands hold price points. The Accuris review described price-pack architecture, meaning changes to pack sizes and price tiers, as the main in-market lever.
- Mondelēz used significant pack downsizing to keep absolute price points accessible.
- Frito-Lay North America cut prices on entry packs, described as a strategic rebase. PepsiCo said in February it would cut prices by up to 15 percent on several Frito-Lay brands ahead of the Super Bowl.
- Coca-Cola Europacific Partners named price and promotion architecture a priority in Germany and cited growth in small formats in France.
- Pernod Ricard listed smaller formats as an affordability tool.
Growth from volume and mix
Pricing is contributing less than in earlier years at some large groups. Nestlé's first-quarter organic growth of 3.5 percent came from 1.2 percent real internal growth and 2.3 percent from pricing, which Accuris called a reversal of 2025's split. Unilever's volumes rose 2.9 percent on 0.9 percent pricing. AB InBev's revenue per hectolitre rose 4.5 percent, which its chief executive attributed mostly to product mix, with about three to three-and-a-half points from inflation.
Premium segments are carrying much of this. Heineken's premium volume rose 5.8 percent while mainstream lager fell, and energy drink volumes grew strongly at Coca-Cola bottlers.
Where pricing power holds, and where it does not
Results are uneven. PepsiCo Beverages North America took 6 percent pricing, lost 2.5 percent volume and still grew 2 percent organically. Frito-Lay North America grew 1 percent with volume up 2 percent and net pricing down 1 percent. Reckitt's North American price and mix fell 2.4 percent, while its infant nutrition unit Mead Johnson gained 4.1 percent in specialty products.
Competition from store brands is a constraint in categories where brand equity is weak. Accuris reported that private label is pressuring value tiers, while Essity and Hill's chose to exit some low-margin private label business, accepting lower volume. The review did not report direct consumer trading-down data.
Geography is diverging as well. Diageo's North American organic sales fell 9.4 percent and Pernod Ricard's US business fell 12 percent, while Nestlé's emerging markets grew 6.8 percent and Reckitt's grew 7.6 percent, according to the same summary.
Promotions are selective
Brands are not discounting everywhere. Colgate's chief executive described more US toothpaste couponing as "nothing tremendously unusual", though the company said it would respond. Coty described a more promotional mass beauty market and Haleon pointed to aggressive competitor promotion in Brazil.
What to watch
- Whether energy-driven costs keep rising and force a new round of price increases.
- Whether shoppers accept smaller packs or begin to notice.
- Whether premium and emerging-market growth can offset weakness in North America.
Bottom line
Persistent inflation is pushing consumer brands toward precision. Where they once raised prices broadly, they now decide pack by pack and market by market where shoppers will pay and where they will walk. The cost pressure has not gone away, so the margin for error is thin.
Nexuswild welcomes factual corrections. Email contact@nexuswild.com with evidence and the article URL.